FD Interest Rates November 2026: Big Updates, Up to 8.60%
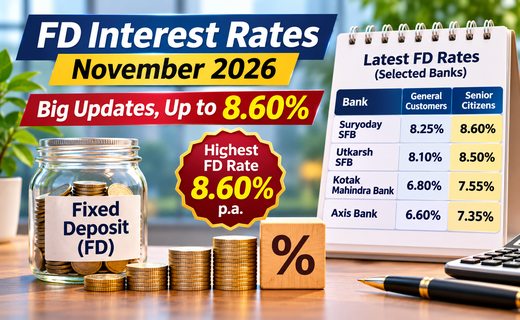
FD Interest Rates November 2026: Big Updates, Up to 8.60%
FD Interest Rates November 2026 have attracted attention as several Indian banks have reportedly revised their fixed deposit offerings. Recent financial news reports highlight advertised annual interest rates reaching 8.60% for eligible senior citizens at selected small finance banks.
Fixed deposits remain popular among Indian savers seeking predictable interest income. However, the highest advertised rate is not necessarily available for every tenure, customer or deposit amount.
Before investing, customers should check the bank’s latest official rate card, effective date and deposit conditions.
FD Interest Rates November 2026: Latest Comparison
Reports published on November 4, 2026, highlighted the following maximum advertised annual rates for selected fixed deposit schemes.
| Bank | General customers | Senior citizens |
|---|---|---|
| Suryoday Small Finance Bank | 8.25% | 8.60% |
| Utkarsh Small Finance Bank | 8.10% | 8.50% |
| Kotak Mahindra Bank | 6.80% | 7.55% |
| Axis Bank | 6.60% | 7.35% |
Important: These are reported maximum rates for selected deposit periods, not standard rates across all tenures. The figures require confirmation against each bank’s current official rate schedule before publication or investment.
The Moneycontrol report on November 2026 FD rates provides the reported comparison.
Which Bank Offers the Highest FD Rate?
Among the four banks in the reported comparison, Suryoday Small Finance Bank offers the highest advertised rate at 8.60% annually for eligible senior citizens.
Its reported maximum general-customer rate is 8.25%.
Utkarsh Small Finance Bank follows with reported maximum rates of 8.50% for senior citizens and 8.10% for general customers.
However, depositors should not select a bank based only on its headline interest rate.
The qualifying tenure, interest payment frequency, premature withdrawal rules and deposit insurance coverage also matter.
Why Do Senior Citizens Receive Higher FD Rates?
Many banks provide additional interest to eligible senior citizens, commonly customers aged 60 years or above.
This benefit can support retirement income, particularly for people who prefer relatively predictable returns.
The additional interest varies by bank and scheme. Some special deposits may also have eligibility restrictions.
Senior citizens should confirm whether the advertised rate applies to their chosen tenure and whether interest will be paid monthly, quarterly or at maturity.
How Safe Are Small Finance Bank FDs?
Small finance banks are regulated banking institutions, but depositors should understand the limits of deposit insurance.
The Deposit Insurance and Credit Guarantee Corporation provides insurance of up to ₹5 lakh per depositor per insured bank, covering eligible principal and interest together.
The limit applies across eligible deposits held in the same capacity and right at that bank, rather than separately to every FD.
Depositors can review the official DICGC deposit insurance information before placing large deposits.
For amounts exceeding the insured limit, spreading savings across different insured banks may help manage concentration risk.
How Much Interest Can ₹1 Lakh Earn?
Consider an illustrative investment of ₹1 lakh for one year at an annual interest rate of 8.60%.
Using simple interest, the calculation is:
₹1,00,000 × 8.60% = ₹8,600
The illustrative total would be ₹1,08,600 before tax.
Actual FD maturity values may differ because banks use specific compounding schedules, deposit tenures and interest payment arrangements.
A quoted rate available only for a five-year deposit should not be assumed to apply to a one-year investment.
FD Taxation and Premature Withdrawal
Interest earned on bank fixed deposits is generally taxable according to the depositor’s applicable income-tax provisions.
Tax deduction at source may apply when relevant thresholds and conditions are met.
Premature withdrawal can also reduce earnings because banks may recalculate interest and impose applicable penalties.
Depositors should compare post-tax returns and liquidity needs before committing funds.
Frequently Asked Questions
Is 8.60% available on every FD?
No. The reported rate applies to a specific eligible customer category and qualifying deposit tenure.
Are FD returns guaranteed?
Contractual FD interest is generally predictable, but bank deposits are not entirely risk-free. Deposit insurance has specified limits.
Can FD rates change after booking?
For a conventional fixed-rate FD, the contracted interest rate generally remains unchanged until maturity.
Conclusion
The FD Interest Rates November 2026 comparison highlights potentially attractive returns at selected banks, especially for senior citizens.
Nevertheless, savers should verify official rates, deposit tenures, taxation and insurance coverage before investing. A suitable FD should balance interest income, safety and access to funds.
Disclaimer: This article provides general financial information, not personalised investment advice. Interest rates and eligibility conditions are subject to change.