NBFC Gold Loan Growth 2026: Lending Surges 66%
NBFC Gold Loan Growth 2026: Lending Surges 66%
NBFC Gold Loan Growth 2026 has accelerated sharply, with outstanding loans against gold jewellery rising 66.1% year-on-year to ₹3.74 lakh crore in September, according to the latest Reserve Bank of India (RBI) sectoral credit data.
The figures, released on November 6, 2026, highlight the growing importance of gold-backed borrowing in India’s non-banking financial sector. For households considering a loan against jewellery, the expansion also raises questions about borrowing costs, repayment obligations and the risk of losing pledged gold.
NBFC Gold Loan Growth 2026: Key RBI Figures
Outstanding gold-jewellery loans increased from approximately ₹2.25 lakh crore in September 2025 to ₹3.74 lakh crore in September 2026.
That represents an increase of nearly ₹1.49 lakh crore within a year.
The RBI’s official sectoral credit release dated November 6 confirms that lending against gold jewellery was among the retail segments experiencing accelerated growth.
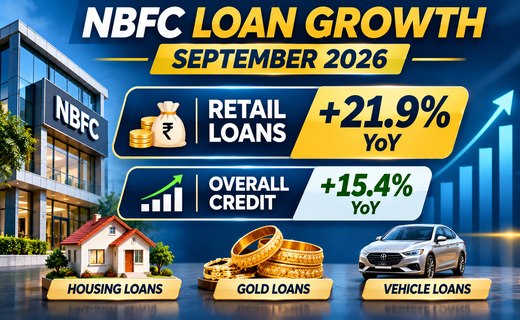
| Lending category | September 2026 outstanding | Annual growth |
|---|---|---|
| Gold-jewellery loans | ₹3.74 lakh crore | 66.1% |
| Overall NBFC retail loans | ₹26.84 lakh crore | 21.9% |
| Vehicle loans | ₹6.46 lakh crore | 16.1% |
| Housing loans | ₹8.70 lakh crore | 12.6% |
| Total NBFC credit | ₹61.69 lakh crore | 15.4% |
The gold-loan figures were independently detailed in Business Standard’s November 6 report.
The data covers a large sample of NBFCs and housing finance companies rather than every lender operating in India.
Why Are Gold Loans Growing So Quickly?
Gold jewellery is widely held by Indian households and can provide collateral for relatively quick borrowing.
When gold prices increase, the market value of pledged jewellery also rises. This may allow eligible borrowers to obtain larger loans, subject to the lender’s valuation and regulatory limits.
Gold-backed loans can appeal to customers seeking short-term liquidity for business expenses, medical bills or other immediate requirements.
However, rapid growth in outstanding loans does not necessarily mean the same percentage increase in the number of borrowers.
Higher collateral valuations and larger average loan amounts may also contribute to the expansion.
How Much Can Borrowers Get Against Gold?
A gold loan’s approved amount depends on the jewellery’s eligible gold content, purity, assessed value and the applicable loan-to-value ratio.
Lenders do not necessarily calculate the loan against the jewellery’s original purchase price or its sentimental value.
Borrowers should request a written valuation statement and understand how the lender determines the eligible collateral value.
Interest rates, processing fees, appraisal charges and repayment structures can vary across lenders.
The lowest advertised interest rate may not represent the cheapest overall loan if additional charges are significant.
What Are the Biggest Gold Loan Risks?
The most important risk is losing pledged jewellery after failing to meet repayment obligations.
Depending on the loan agreement and applicable regulatory requirements, a lender may initiate recovery procedures, including an auction of collateral.
Borrowers should understand the notice process, repayment deadlines and treatment of any surplus auction proceeds.
Gold-price movements can also affect collateral coverage. A decline in gold prices may create additional repayment or security requirements where the applicable terms permit them.
The RBI’s NBFC Credit Facilities Directions contain regulatory provisions covering gold and silver collateral, including valuation and lender policies.
Are Rising Gold Loans a Warning Sign?
The rapid expansion deserves attention, but it should not automatically be interpreted as evidence of widespread borrower distress.
Gold-backed borrowing can support legitimate household and business liquidity needs.
Nevertheless, refinancing existing debt through another secured loan can increase financial vulnerability if the borrower has no realistic repayment plan.
Business Standard reported industry concerns about some gold-loan disbursements involving borrowers with significantly overdue existing loans.
That observation warrants caution but does not establish that all gold-loan borrowers are financially stressed.
What Should Borrowers Check Before Applying?
Before pledging jewellery, compare the total borrowing cost across lenders, including interest, processing fees and potential overdue charges.
Confirm whether repayment requires regular instalments, periodic interest payments or a lump sum at maturity.
Ask how the jewellery will be stored, insured and returned after full repayment.
Most importantly, borrow only an amount that can be repaid without relying on uncertain future income.
The RBI’s latest figures show how rapidly gold-backed lending is expanding. For borrowers, however, the essential decision remains personal: whether the immediate benefit of obtaining funds justifies the cost and the risk to valuable family assets.
Disclaimer: This article is for general information and does not constitute financial advice. Loan terms and regulatory requirements vary by lender and product. Review official documents before borrowing.