RBI Domestic Money Transfer Rules 2026: Key Limits
RBI Domestic Money Transfer Rules 2026: Key Limits
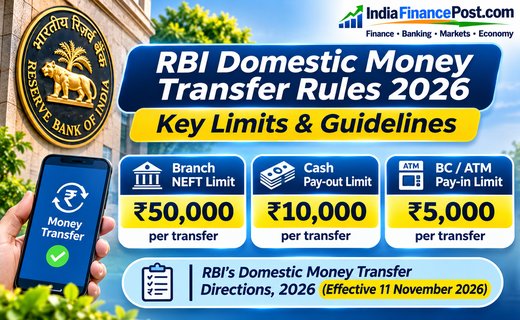
The RBI Domestic Money Transfer Rules 2026, issued on November 11, consolidate the Reserve Bank of India’s existing instructions for domestic remittances. The directions cover certain cash-based money transfers through banks and authorised business correspondents, with requirements for customer identification, transaction records and monitoring.
Importantly, the RBI has retained existing transaction limits, rather than introducing new limits on all bank transfers. Customers using regular account-to-account NEFT, IMPS or UPI services should not confuse these specialised remittance rules with general digital payment limits.
RBI Domestic Money Transfer Rules 2026: Key Details
The consolidated directions took effect immediately after their issuance. They bring applicable instructions together to help regulated institutions follow a consistent framework.
| Transfer facility | Applicable limit |
|---|---|
| Cash remittance through branch NEFT | ₹50,000 per transaction |
| Cash pay-out to beneficiary | ₹10,000 per transaction |
| Cash pay-in through BC or ATM | ₹5,000 per transaction |
These limits apply to the relevant domestic money transfer facilities and should not be interpreted as universal limits on every bank transaction.
Customers should check their bank’s specific service conditions, applicable charges and identification requirements before initiating a remittance.
What Has Changed Under the New Directions?
The November 2026 directions consolidate the regulatory framework rather than announce an entirely new domestic transfer system.
The RBI continues to require banks and participating institutions to maintain appropriate customer identification and transaction-monitoring procedures.
For eligible cash-based remittances, institutions must follow prescribed information collection and record-keeping requirements.
These safeguards are intended to improve traceability and reduce misuse of remittance services.
The notification does not mean every customer must complete a fresh verification process for ordinary UPI or account-based transfers.
Who Will Be Affected?
The directions are particularly relevant to people who use cash-based domestic remittance facilities.
These may include migrant workers sending money to family members, customers without convenient access to full banking services and people using authorised business correspondents.
For example, a worker depositing cash through an eligible remittance channel may face a different transaction ceiling from someone transferring funds directly between two verified bank accounts.
Understanding the distinction can help customers avoid failed transactions or unnecessary visits to bank branches.
Does This Affect UPI, IMPS and NEFT?
The directions should not be mistaken for a general reduction in UPI, IMPS or NEFT transfer limits.
The ₹50,000 branch NEFT provision concerns eligible cash remittances. It does not impose a universal ₹50,000 ceiling on account-funded NEFT transfers.
Similarly, the ₹5,000 and ₹10,000 limits relate to specified cash pay-in and pay-out facilities.
Regular electronic transfers remain subject to their applicable payment-system rules, bank policies and risk controls.
Customers should confirm the precise service being used before comparing transaction limits.
Why Does the RBI Regulate Domestic Remittances?
Domestic money transfer services help individuals move funds across locations, including where traditional banking access is limited.
However, cash-based transactions require safeguards because identifying the sender and tracing payments can be more challenging.
Customer verification, transaction records and monitoring help financial institutions detect suspicious activity and maintain compliance.
The RBI’s consolidated framework aims to preserve access to remittance services while maintaining regulatory oversight.
What Should Bank Customers Do?
Customers planning a cash-based transfer should verify the applicable limit, recipient details, service availability and charges.
They should carry the identification information required by the service provider and obtain a transaction receipt or confirmation.
Never share an OTP, PIN or banking password with anyone claiming to process or accelerate a transfer.
If a transaction fails or money is not received, contact the bank or authorised service provider through its official support channel.
Frequently Asked Questions
Are the RBI transfer limits new?
No. The November 2026 directions retain existing limits for specified domestic remittance services.
Is every NEFT transfer limited to ₹50,000?
No. The ₹50,000 provision applies to the specified cash-remittance facility, not all account-based NEFT transactions.
Do these rules reduce UPI limits?
No general reduction in UPI transfer limits is established by these directions.
Conclusion
The RBI Domestic Money Transfer Rules 2026 consolidate important safeguards for cash-based remittances while retaining existing transaction ceilings.
For customers, the key is understanding which transfer facility they are using. Ordinary digital payments and specialised cash-remittance services operate under different requirements.
Official source: Reserve Bank of India — Domestic Money Transfer Directions, 2026
Disclaimer: This article provides general banking information. Transaction limits, charges and service eligibility should be confirmed with the relevant bank or authorised provider.