How to Start a Business in India: Step-by-Step Guide
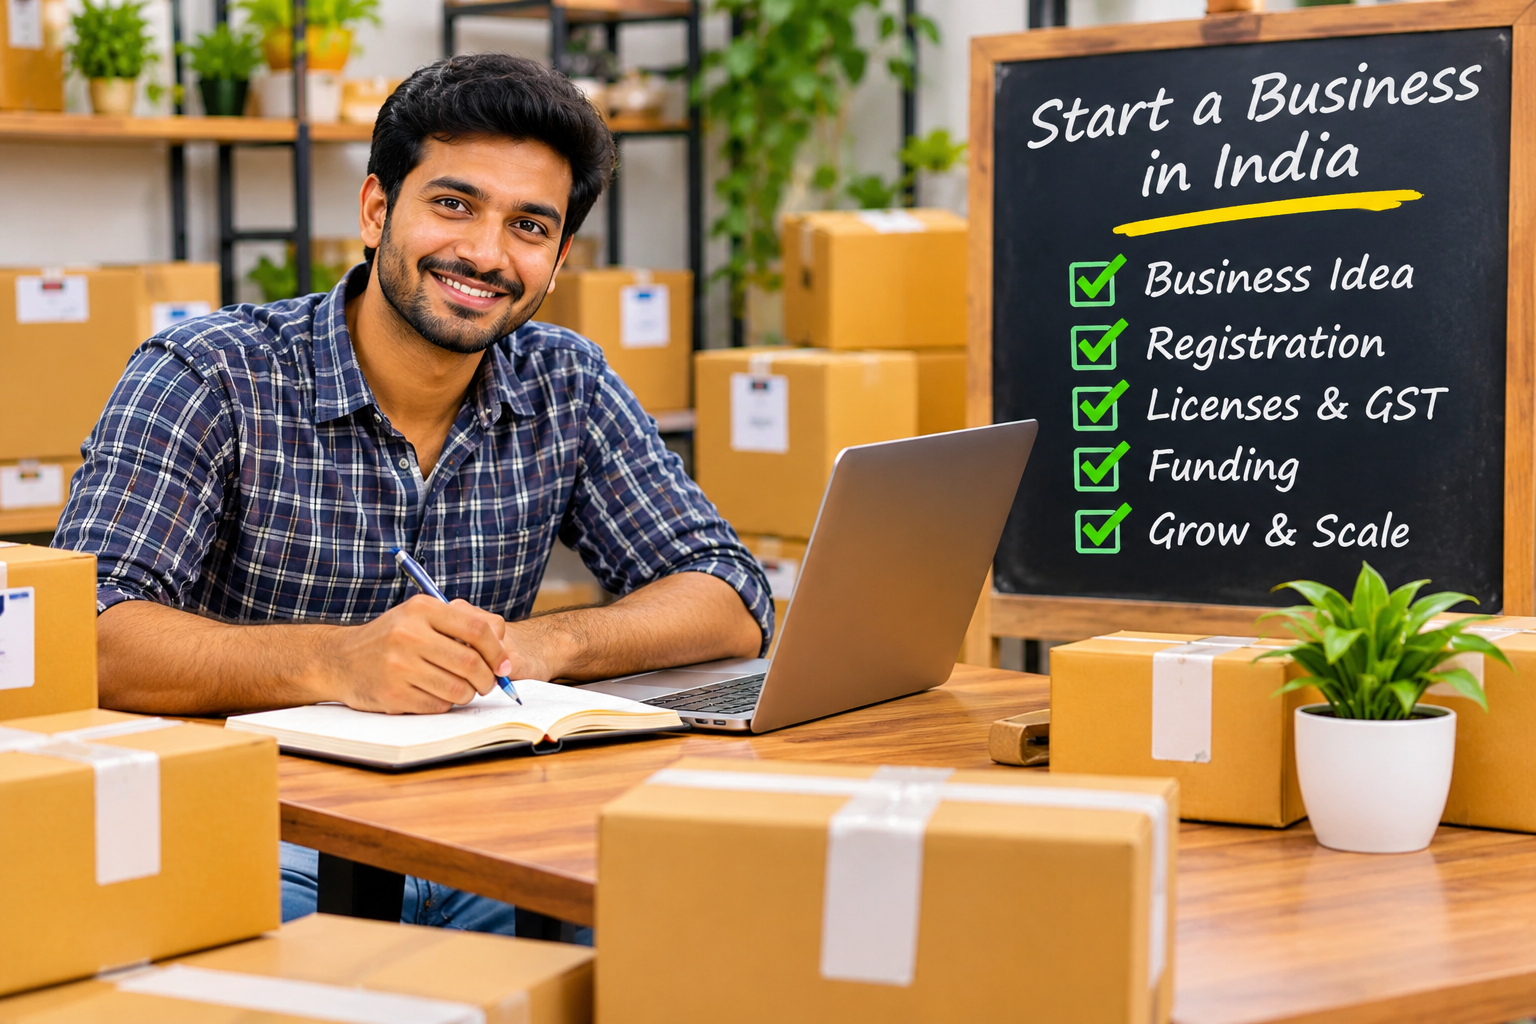
How to Start a Business in India: Step-by-Step Guide
Planning to start a business in India? Whether you want to launch an online store, technology startup, consulting service or small manufacturing unit, building a successful business requires more than a promising idea.
Entrepreneurs must understand customer demand, choose the right business structure, manage finances, comply with applicable regulations and develop a sustainable growth strategy.
This step-by-step guide explains how to start a business in India, including registration, funding options, government initiatives, taxation and common mistakes to avoid.
Why Start a Business in India?
India offers opportunities for entrepreneurs across technology, manufacturing, retail, financial services, education, logistics and other sectors.
Digital payments, e-commerce platforms and online business tools have made it easier for many small businesses to reach customers without opening large physical offices.
However, starting a business still involves financial risks, competition and regulatory responsibilities.
A successful business should begin with a clear understanding of the problem it solves and the customers willing to pay for its products or services.
Step 1: Choose a Profitable Business Idea
Before you start a business in India, identify a product or service that addresses a genuine customer need.
A business idea should be evaluated using several factors:
- Customer demand: Are people actively looking for this solution?
- Competition: Which businesses already serve the market?
- Pricing: What are customers willing to pay?
- Startup costs: How much money is needed to launch?
- Profit potential: Can revenue cover operating expenses?
- Scalability: Can the business grow without costs rising at the same rate?
For example, a home-based digital marketing agency may require less initial investment than a manufacturing business that needs machinery, storage and employees.
Rather than investing heavily immediately, entrepreneurs can test demand with a limited offering.
Step 2: Conduct Market Research
Market research helps entrepreneurs understand potential customers and avoid unnecessary expenditure.
Start by identifying your target audience, including their location, purchasing habits, budget and preferences.
Study competitors’ prices, customer reviews and service quality.
You can also conduct surveys, interview potential customers or launch a small pilot project.
How to Validate Your Startup Idea
Suppose you plan to start an online clothing business.
Before purchasing large quantities of inventory, you could introduce a limited collection and track customer enquiries, sales and returns.
If customers respond positively, expand gradually.
This approach can reduce the financial risk of launching an untested product.
Step 3: Prepare a Business Plan
A business plan provides a roadmap for operations, financing and future growth.
Your plan should include:
- Business concept and objectives.
- Target customers and market size.
- Products or services.
- Competitor analysis.
- Marketing and sales strategy.
- Startup investment requirements.
- Monthly operating expenses.
- Revenue and profitability projections.
- Major business risks.
Example Startup Budget
The following is an illustrative budget for a small service-based business, not a standard cost of registration or incorporation.
| Expense | Estimated Amount |
|---|---|
| Laptop and equipment | ₹40,000 |
| Website and software | ₹15,000 |
| Marketing | ₹20,000 |
| Professional and administrative expenses | ₹10,000 |
| Working capital reserve | ₹65,000 |
| Total | ₹1,50,000 |
Actual costs vary significantly depending on business type, location and scale.
Step 4: Choose the Right Business Structure
Selecting the appropriate legal structure is an important decision when you start a business in India.
Sole Proprietorship
A sole proprietorship is owned and operated by one individual.
It can be suitable for small businesses, freelancers and independent service providers.
However, the proprietor generally has unlimited personal liability for business obligations.
Partnership Firm
A partnership allows two or more individuals to operate a business together under an agreed arrangement.
A written partnership deed can clarify responsibilities, profit sharing and decision-making.
Limited Liability Partnership (LLP)
An LLP provides a separate legal identity and limited liability protection, subject to applicable law.
It may suit professional services and businesses that want a more formal structure.
Private Limited Company
A private limited company is a separate legal entity that can be suitable for startups planning to raise external investment.
However, incorporation and ongoing statutory compliance involve additional responsibilities.
Entrepreneurs should compare legal liability, taxation, compliance costs and future fundraising requirements before choosing.
Step 5: Register Your Business
Business registration requirements depend on the selected structure.
For companies and LLPs, the Ministry of Corporate Affairs provides official online incorporation services.
Official website: Ministry of Corporate Affairs
Depending on the structure, the process may involve obtaining digital signatures, submitting incorporation forms and providing details of owners, directors or partners.
A sole proprietorship does not have the same central incorporation process as a company, but it may require applicable tax registrations, local licences or other business documentation.
Documents Commonly Required
Depending on the business structure, documents may include:
- PAN and identity documents.
- Address proof.
- Registered office address documentation.
- Owner, partner or director details.
- Digital signatures where required.
- Additional declarations or approvals.
Requirements should always be checked against the official registration portal.
Step 6: Understand GST and Business Licences
Not every new business must immediately register for GST.
GST registration depends on turnover, business activities, location and other statutory conditions.
Certain transactions or business models may trigger registration obligations even when turnover is below the general threshold.
Entrepreneurs should verify their eligibility through the official GST Portal.
Depending on the industry, additional approvals may include:
- Local trade licences.
- Shops and Establishments registration.
- FSSAI registration or licence for eligible food businesses.
- Import Export Code for applicable import-export activities.
- Industry-specific permissions.
Business registration alone does not replace these approvals.
Step 7: Explore Startup India and MSME Registration
The Government of India provides several initiatives to support eligible entrepreneurs.
Startup India Recognition
The Startup India initiative offers a framework through which qualifying entities may apply for recognition by the Department for Promotion of Industry and Internal Trade (DPIIT).
Recognition depends on prescribed criteria, including the entity’s legal form, age, turnover and innovation-related conditions.
DPIIT recognition does not automatically guarantee funding, tax exemptions or government contracts.
Official source: Startup India
Udyam MSME Registration
Eligible micro, small and medium enterprises can obtain Udyam Registration through the government’s free online portal.
MSME registration and DPIIT startup recognition are different processes.
A qualifying business may be eligible for one or both, depending on the applicable rules.
Official source: Udyam Registration
Step 8: Arrange Startup Funding
Entrepreneurs can consider different financing options depending on the business model and financial requirements.
Personal Savings
Self-funding allows entrepreneurs to retain ownership but exposes their personal savings to business risk.
Bank Business Loans
Banks may provide working capital or term loans based on eligibility, financial information, repayment capacity and lending policies.
Government-Linked Credit Schemes
Eligible businesses may explore schemes such as Pradhan Mantri MUDRA Yojana and applicable MSME credit-support programmes.
Scheme availability, loan amounts and eligibility conditions should be verified with participating lenders and official government sources.
Angel Investors and Venture Capital
Startups with scalable business models may seek external investment.
However, investment funding can involve dilution of ownership, investor rights and additional reporting obligations.
Step 9: Build Your Online Presence
A digital presence can help a new business attract customers and establish credibility.
Consider creating:
- A professional website.
- A business email address.
- Relevant social media profiles.
- A Google Business Profile, where eligible.
- A secure payment collection system.
- A customer support process.
Focus on channels where your target customers are most active rather than spending money on every marketing platform.
Step 10: Track Revenue, Expenses and Profit
Many new entrepreneurs focus on sales but overlook cash flow.
Revenue represents money earned from selling products or services.
Profit is what remains after deducting applicable expenses.
Cash flow measures the movement of money into and out of the business.
A company may report sales but still struggle to pay suppliers if customers delay payments.
Basic Financial Example
Suppose a small business generates ₹1,00,000 in monthly revenue.
| Particulars | Monthly Amount |
|---|---|
| Revenue | ₹1,00,000 |
| Product or service costs | ₹40,000 |
| Rent and utilities | ₹15,000 |
| Marketing | ₹10,000 |
| Other operating expenses | ₹15,000 |
| Illustrative operating surplus | ₹20,000 |
This example excludes certain potential costs, taxes, financing charges and owner compensation. It is not a guaranteed profit projection.
Maintaining accurate financial records helps entrepreneurs make better decisions.
Common Mistakes New Entrepreneurs Should Avoid
When planning to start a business in India, avoid these common mistakes:
Starting without market research: An attractive idea does not automatically guarantee customer demand.
Spending too much before launch: Large initial investments can create financial pressure.
Ignoring legal requirements: Missing registrations, licences or tax obligations may lead to penalties.
Mixing personal and business finances: Separate financial records make bookkeeping and performance tracking easier.
Depending on one customer: Revenue concentration can create serious business risk.
Ignoring cash flow: Profitable-looking businesses can still face payment difficulties.
Frequently Asked Questions
How much money is needed to start a business in India?
Startup costs depend on the industry, legal structure, equipment, location and operating model. Some service businesses can begin with relatively limited capital, while manufacturing businesses may require substantial investment.
Can I start a business in India without registering a company?
Yes. Certain businesses can operate as sole proprietorships without incorporating a company, although applicable licences and tax registrations may still be required.
Is Startup India registration free?
The government’s DPIIT recognition application does not require a government application fee. Professional service charges, if voluntarily used, are separate.
Is GST mandatory for every startup?
No. GST registration depends on the applicable legal requirements, not simply on whether a business is new.
Can a startup apply for an MSME loan?
Eligible startups may apply for relevant business credit products or schemes, subject to lender assessment and programme conditions.
Final Thoughts
Choosing to start a business in India can create opportunities for financial independence, innovation and long-term growth.
However, successful entrepreneurship requires careful planning, realistic budgeting, appropriate legal compliance and continuous attention to customer needs.
Start small where practical, validate demand, maintain accurate financial records and expand when the business model demonstrates sustainable potential.
For official guidance, refer to the Ministry of Corporate Affairs, Startup India, the GST Portal and the Udyam Registration Portal.
Disclaimer: This article is for general educational purposes only and does not constitute legal, tax, investment or financial advice. Registration requirements and government schemes may change.